Right now, gold miners are the cheapest they’ve been in 50 years.
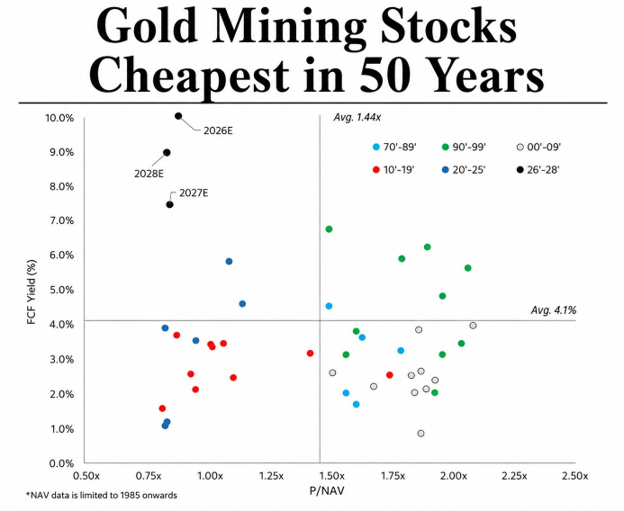
This chart (h/t Lukas Ekwueme @ekwufinance)shows the free cash flow yield for miners currently (the upper left quadrant) as well as for decades going back 50 years.
Free cash flow is simply the money left over after every cost of the business is accounted for. Other metrics like PE, EBITDA, price to book, etc. often mask the real story of profitability behind accounting tricks, depreciation, etc.
The cash left over after EVERYTHING is accounted for tells a very simple story about a business – which is: how much cash does this business really create.
The yield percentage is calculated by dividing market cap by free cash flow – which tells you how much cash is generated by the business as a percentage of its price.
And right now, the whole gold miner sector is projecting 9%-10% free cash flow yields over the next year. Based on this metric, gold miners are also the cheapest sector in the market right now. The only sector that comes close is energy, which is selling for about 7% FCF yield.
To put that FCF yield in context, the biggest tech stocks on earth like Microsoft, Amazon, Google and Nvidia all sell for less than 4% free cash flow.
You’re paying at 3X as much for the productive businesses underlying these high-flying tech stocks than you pay for an average gold miner.
Some tech stocks like Palantir are even more expensive – selling for just 0.8% yield on FCF. Palantir would have to fall 90% in price to have the same yield as the average gold miner.
Nvidia might be a world-changing company with cutting edge chip tech and incredible market saturation, but it’s selling for 2% FCF yields… meaning that if it reaches parity with gold stock FCF yields, Nvidia’ stock price would have to fall 80%.
Or, as I believe is more likely: gold miners will rise until these sky-high FCF yields return to a normal level of 4%…
That would mean we would see gold miner stocks more than double in price.
Right now, the most popular stocks in the world are priced beyond perfection. Tesla and Palantir both have 12-month average PE ratios of more than 200X earnings. That’s getting into “Cisco in 2000” levels.
I’m not saying we’re going to see a tech crash like we did in 2000. I’m just saying: most people don’t own any gold stocks at all…
And gold stocks are the cheapest they’ve been in 5 decades.
He Woke Up 79% Richer
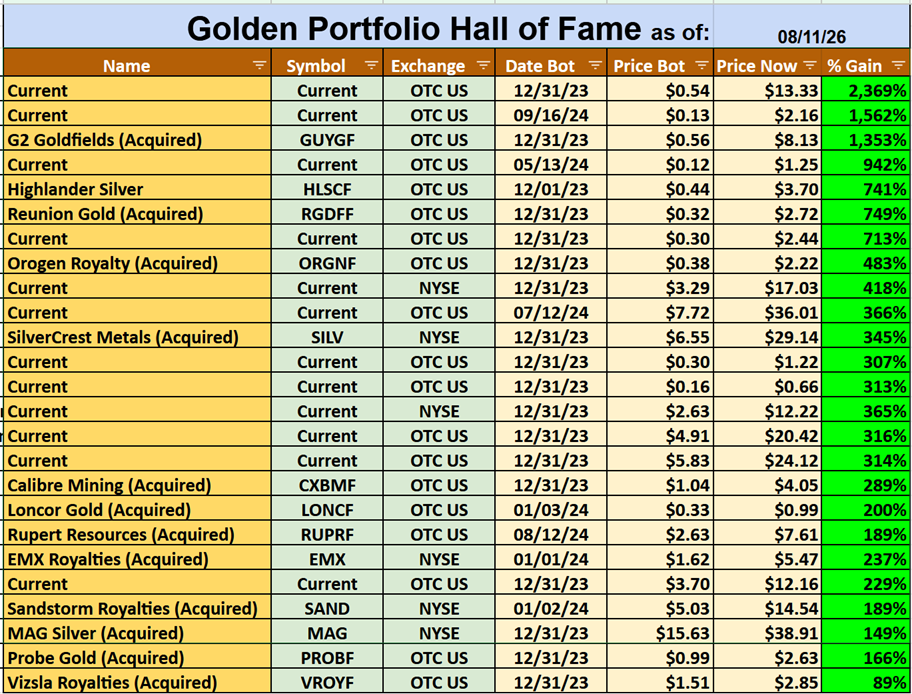
It’s the strangest way I know to make money in gold… You go to bed owning a small miner, and overnight, a major announces it’s buying the company. No chart to time, no exit to nail — your shares simply reprice while you sleep. One quarter of my portfolio has already been acquired by the major gold miners in the space, with overnight pops as high as 79%. Best of all… the wave of buyouts has barely started.
Go here to see who I think gets bought next.
I don’t believe this scenario will last long. Money tends to move into sectors where it is treated best – eventually. Even the most bullish tech investors will at some point concede that Nvidia is unlikely to generate 5x more cash flow in the coming 12 months. The valuations are just not likely.
It is true that gold stocks are hated and widely misunderstood. That means investment into this sector will be lumpy and unpredictable. But it also means we’re likely to see some absurd gains in the coming years as money flows into gold miners. As silly as we’ve seen some of the valuations in tech stocks, I believe we could see similarly unreal valuations in gold stocks. But we’re nowhere close… Every gold stock in my portfolio is currently well under my fair value price targets.
If you’re looking for a signal to get bullish on gold stocks, it doesn’t get any clearer.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio